The best budget planner depends on whether you want a compact monthly tracker, a detailed bill organizer, or a broader life planner with budgeting pages. These five options cover monthly and biweekly formats, with differences in size, savings and debt tracking, and space for cash or receipts.
Quick Top Products
Clever Fox Budget Book 2.0
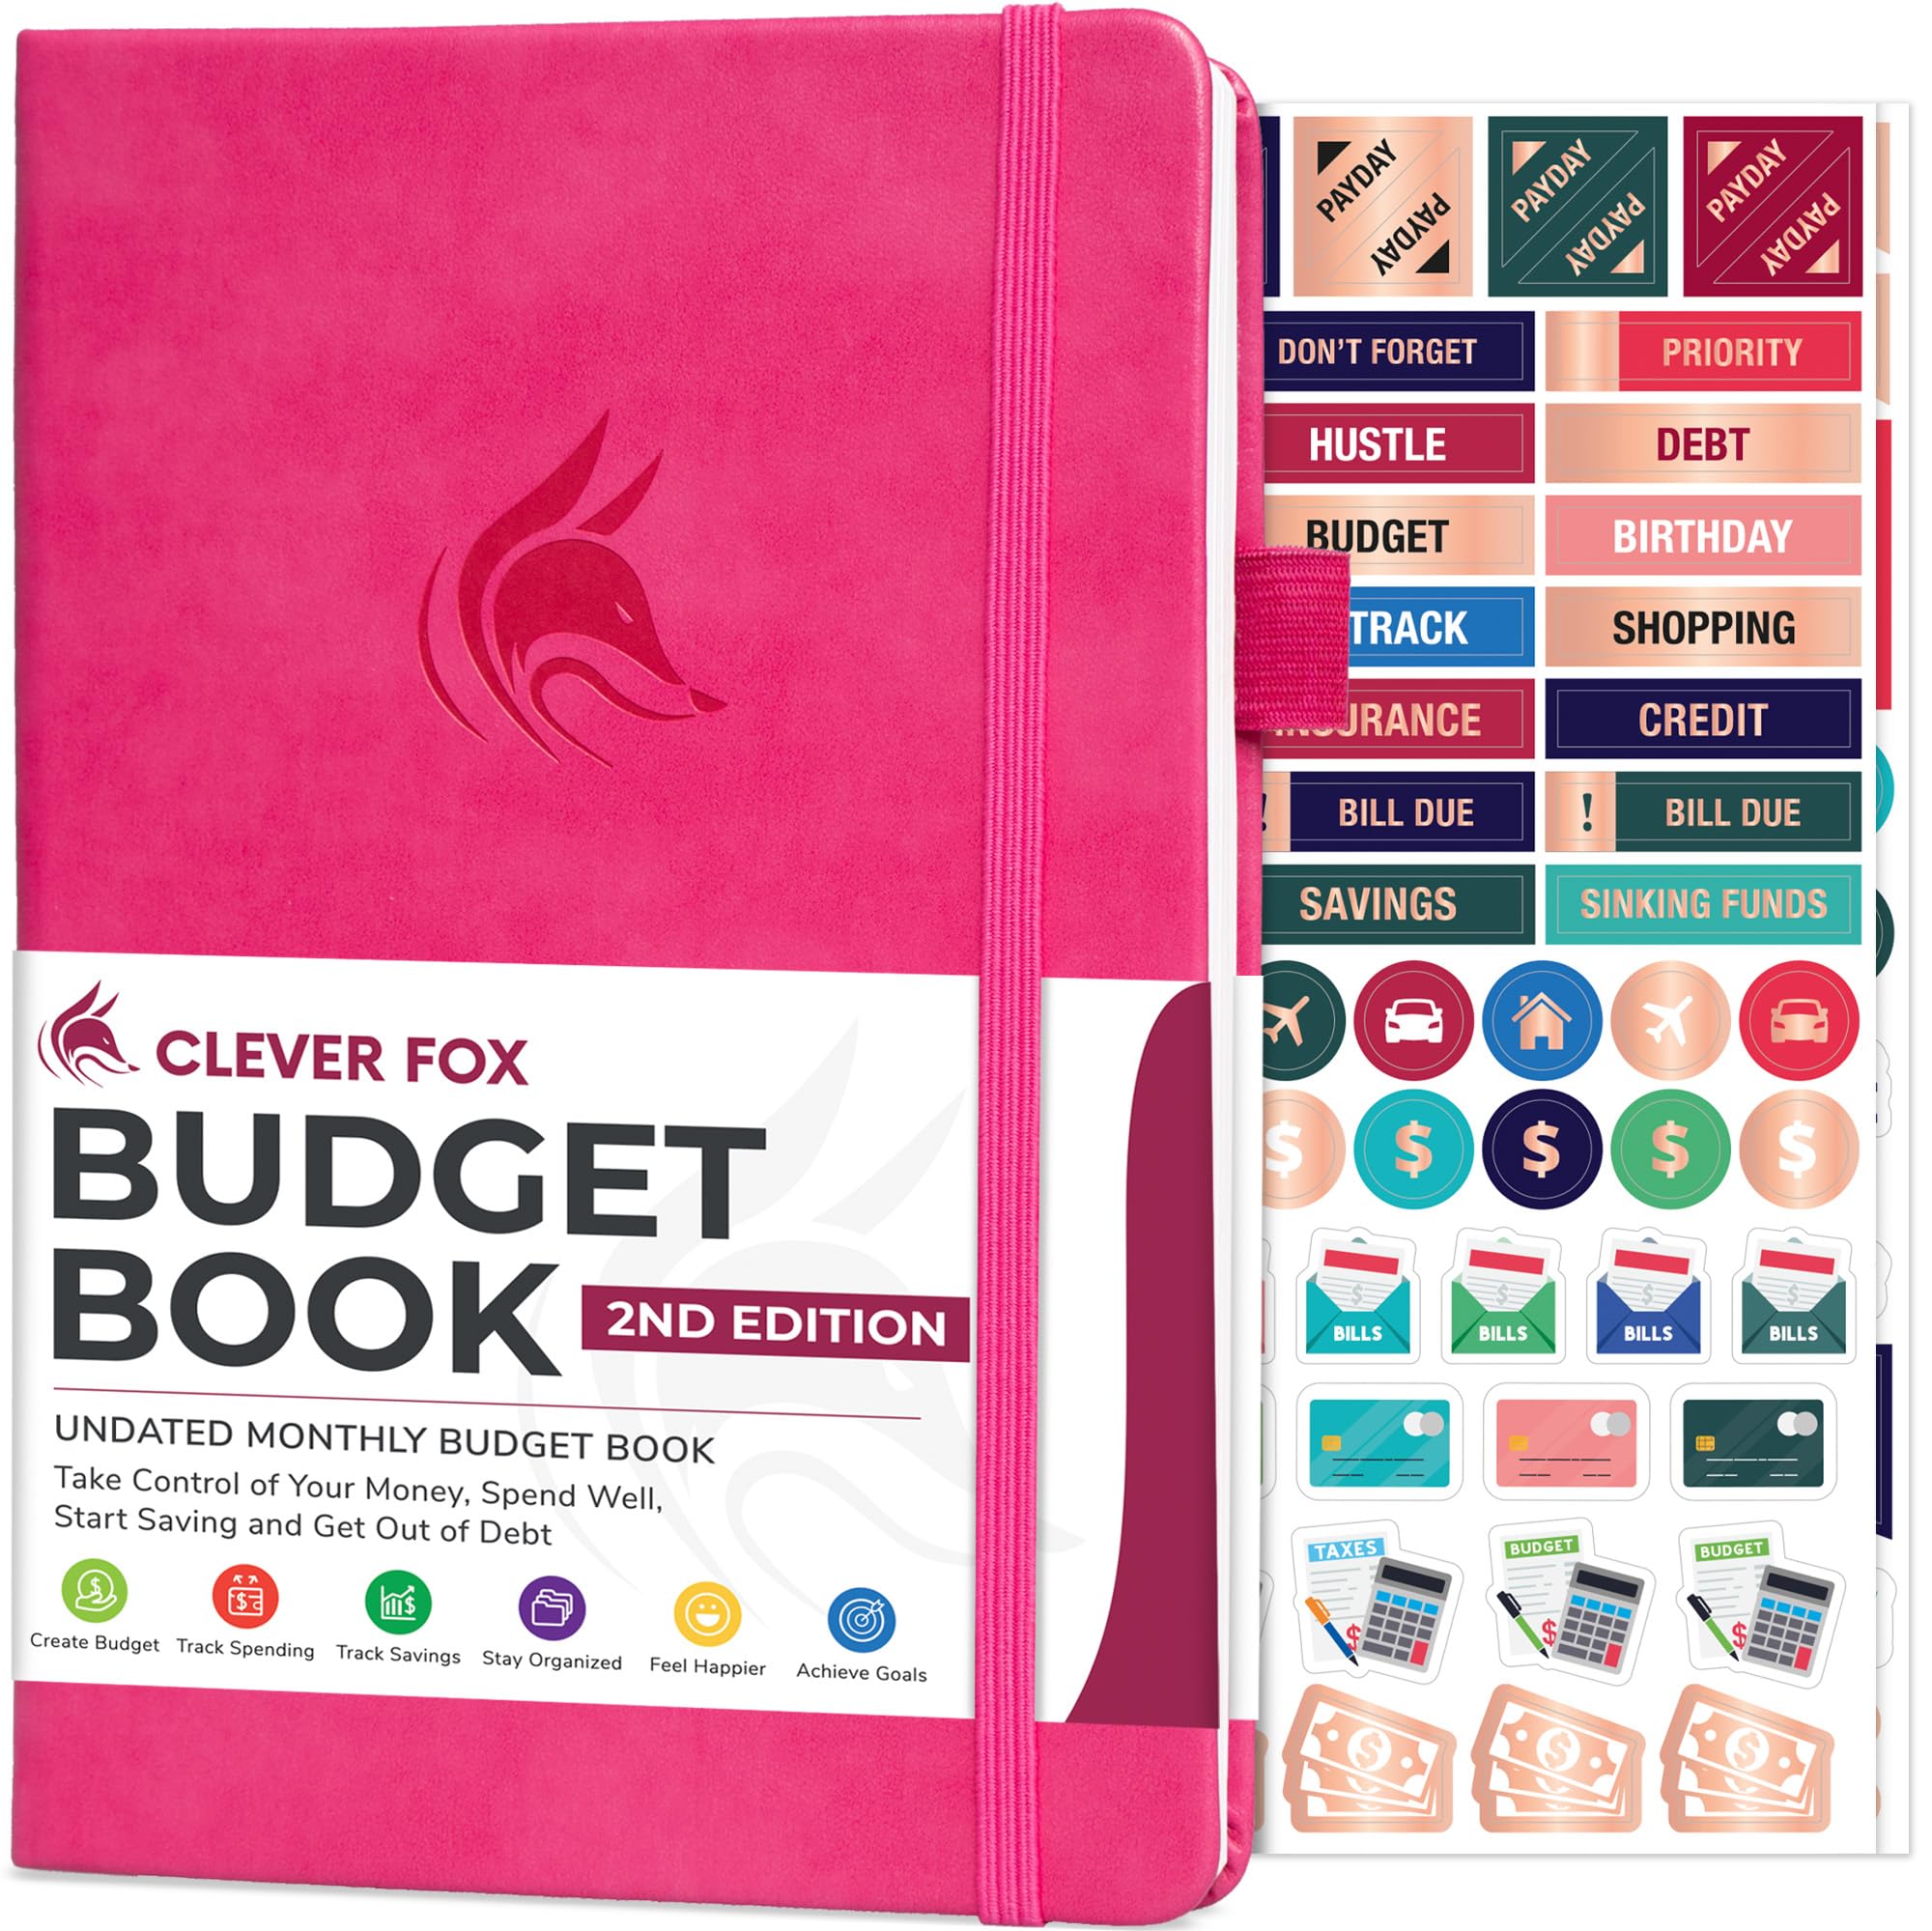
- Compact 5.3 by 7.7 inch format with monthly planning pages.
- Includes eight savings and eight debt trackers, plus a bill tracker.
- Has a receipt pocket, pen loop, and ribbon bookmark.
Best For: Beginners who want a portable monthly planner with dedicated savings, debt, and bill trackers.

Clever Fox Bi Weekly Budget Planner
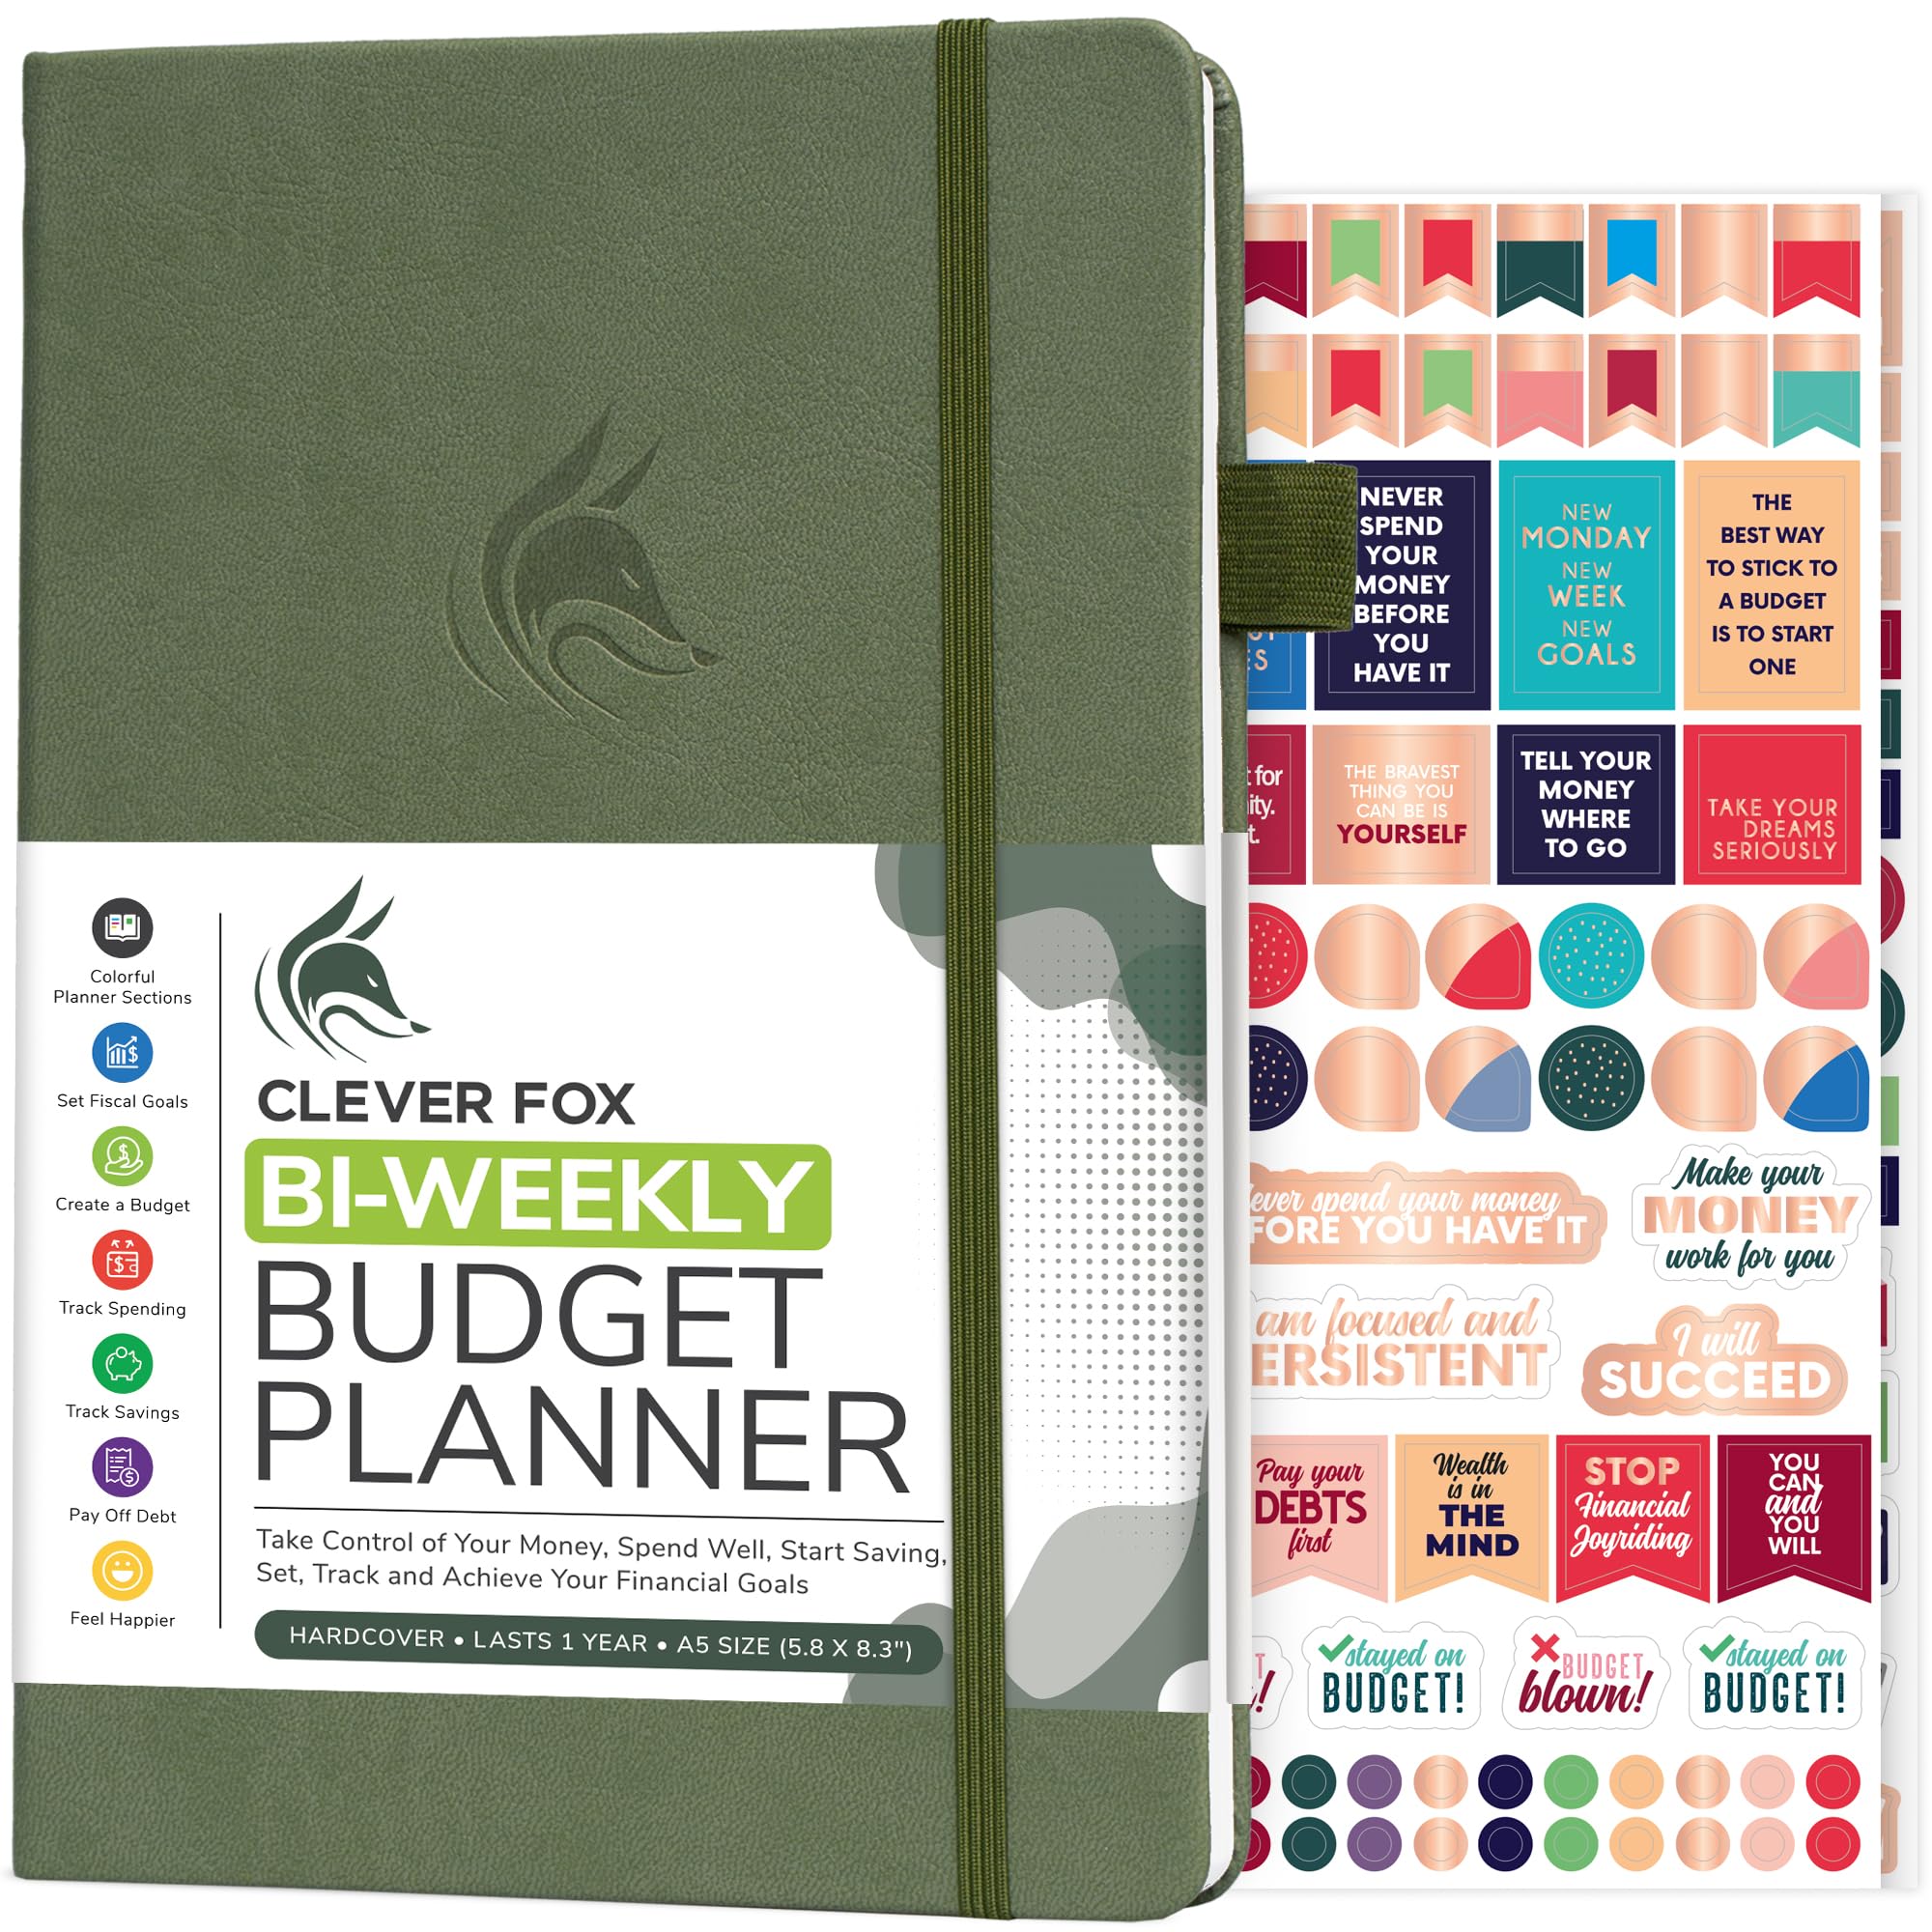
- Undated planner with detailed biweekly budgeting spreads.
- Tracks important dates, payment deadlines, and daily expenses.
- A5 format includes lay-flat binding and a receipt pocket.
Best For: People who prefer to organize budgets and payment deadlines in biweekly sections.
Clever Fox Budget Planner & Monthly Bill Organizer
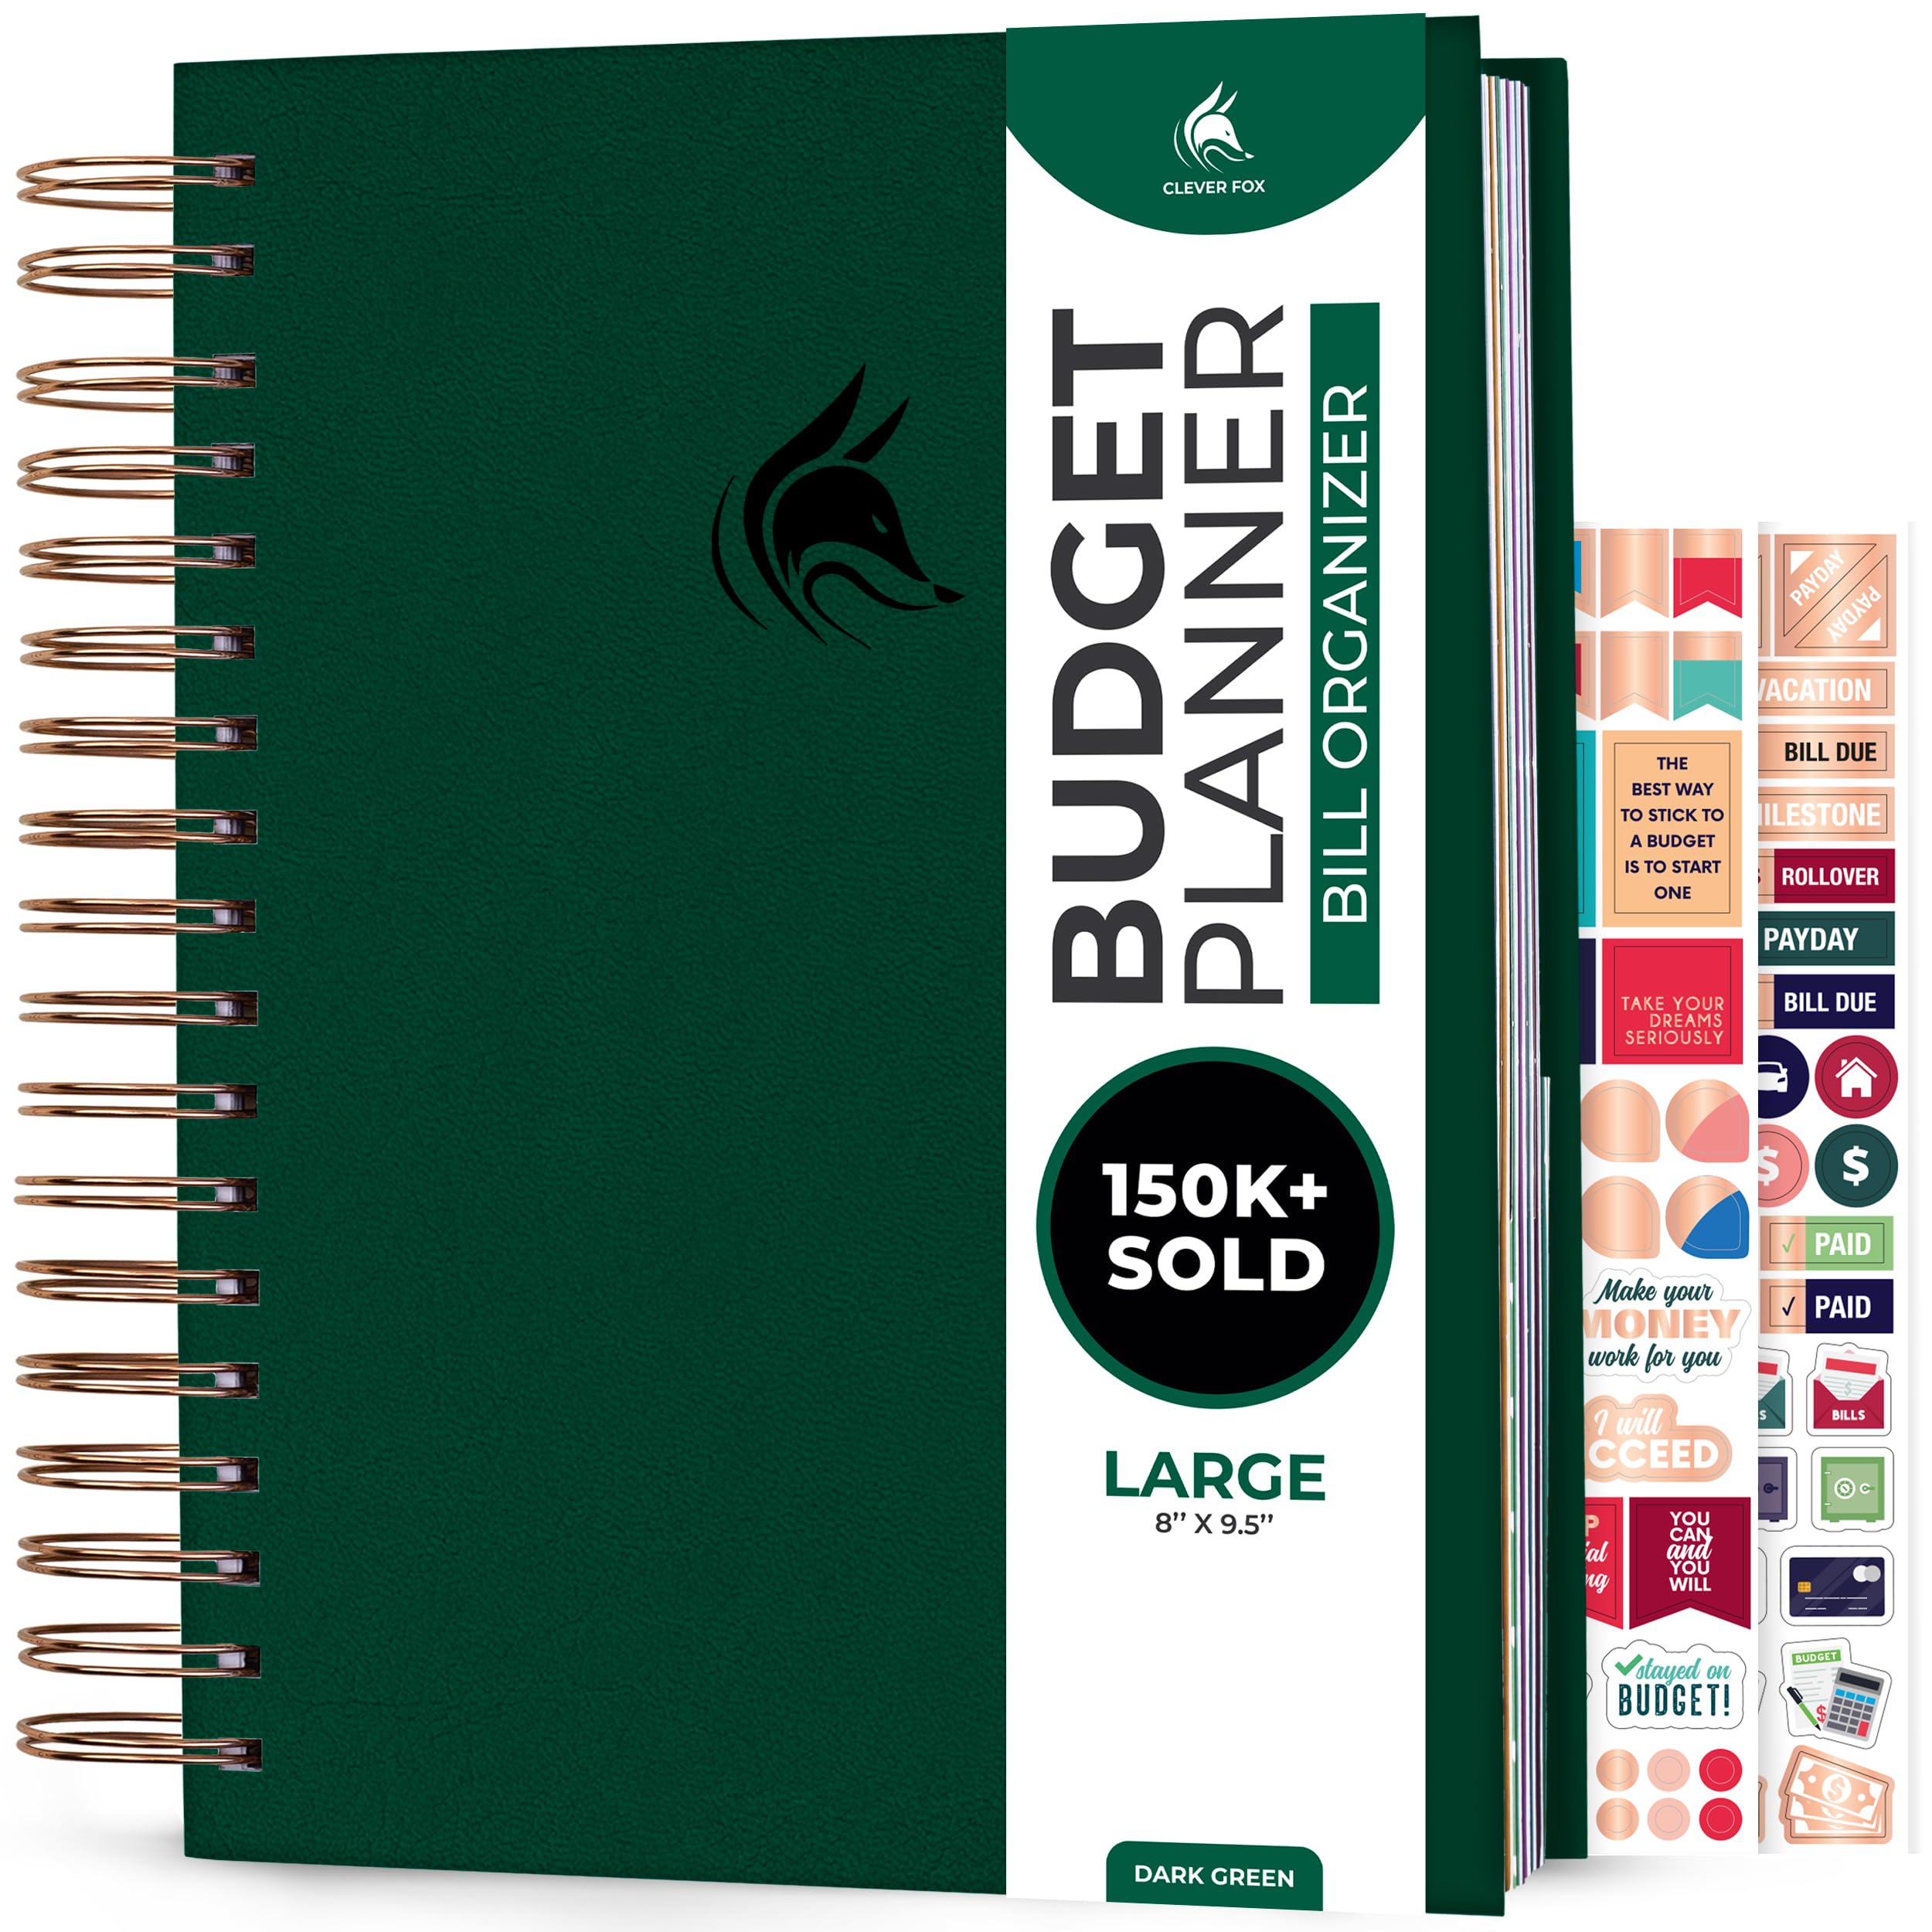
- Large 8 by 9.5 inch format with spiral binding.
- Includes twelve laminated bill pockets for financial papers.
- Supports monthly spending plans, daily expense tracking, and goal setting.
Best For: Households that want monthly expense tracking alongside labeled storage for bill paperwork.
Clever Fox Budget Planner Spiral
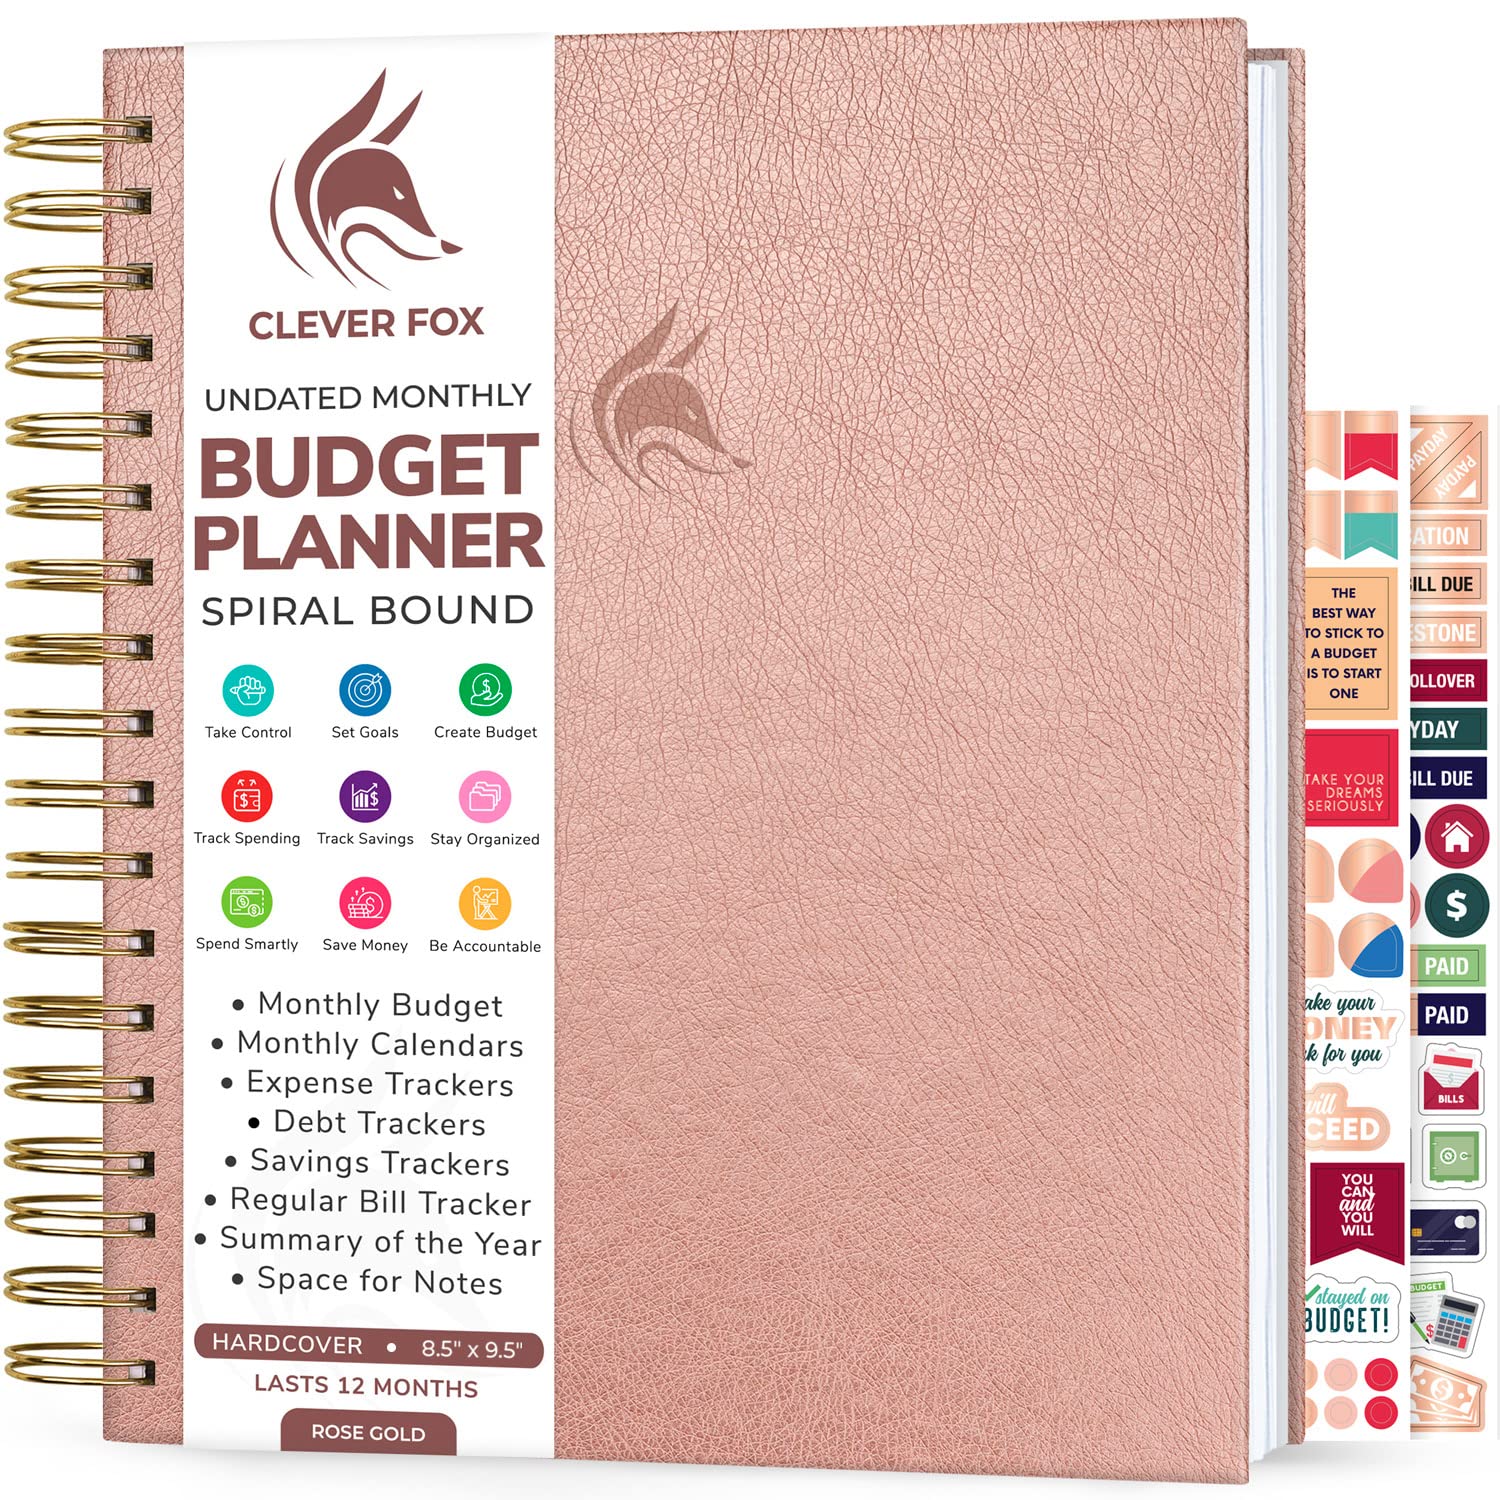
- Undated layout lasts twelve months and includes monthly reviews.
- Includes eight savings and twelve debt trackers.
- Large 8.5 by 9.5 inch format comes with three cash envelopes.
Best For: Budgeters who want a large monthly planner with cash envelopes, savings, and debt trackers.
Clever Fox Planner PRO Premium
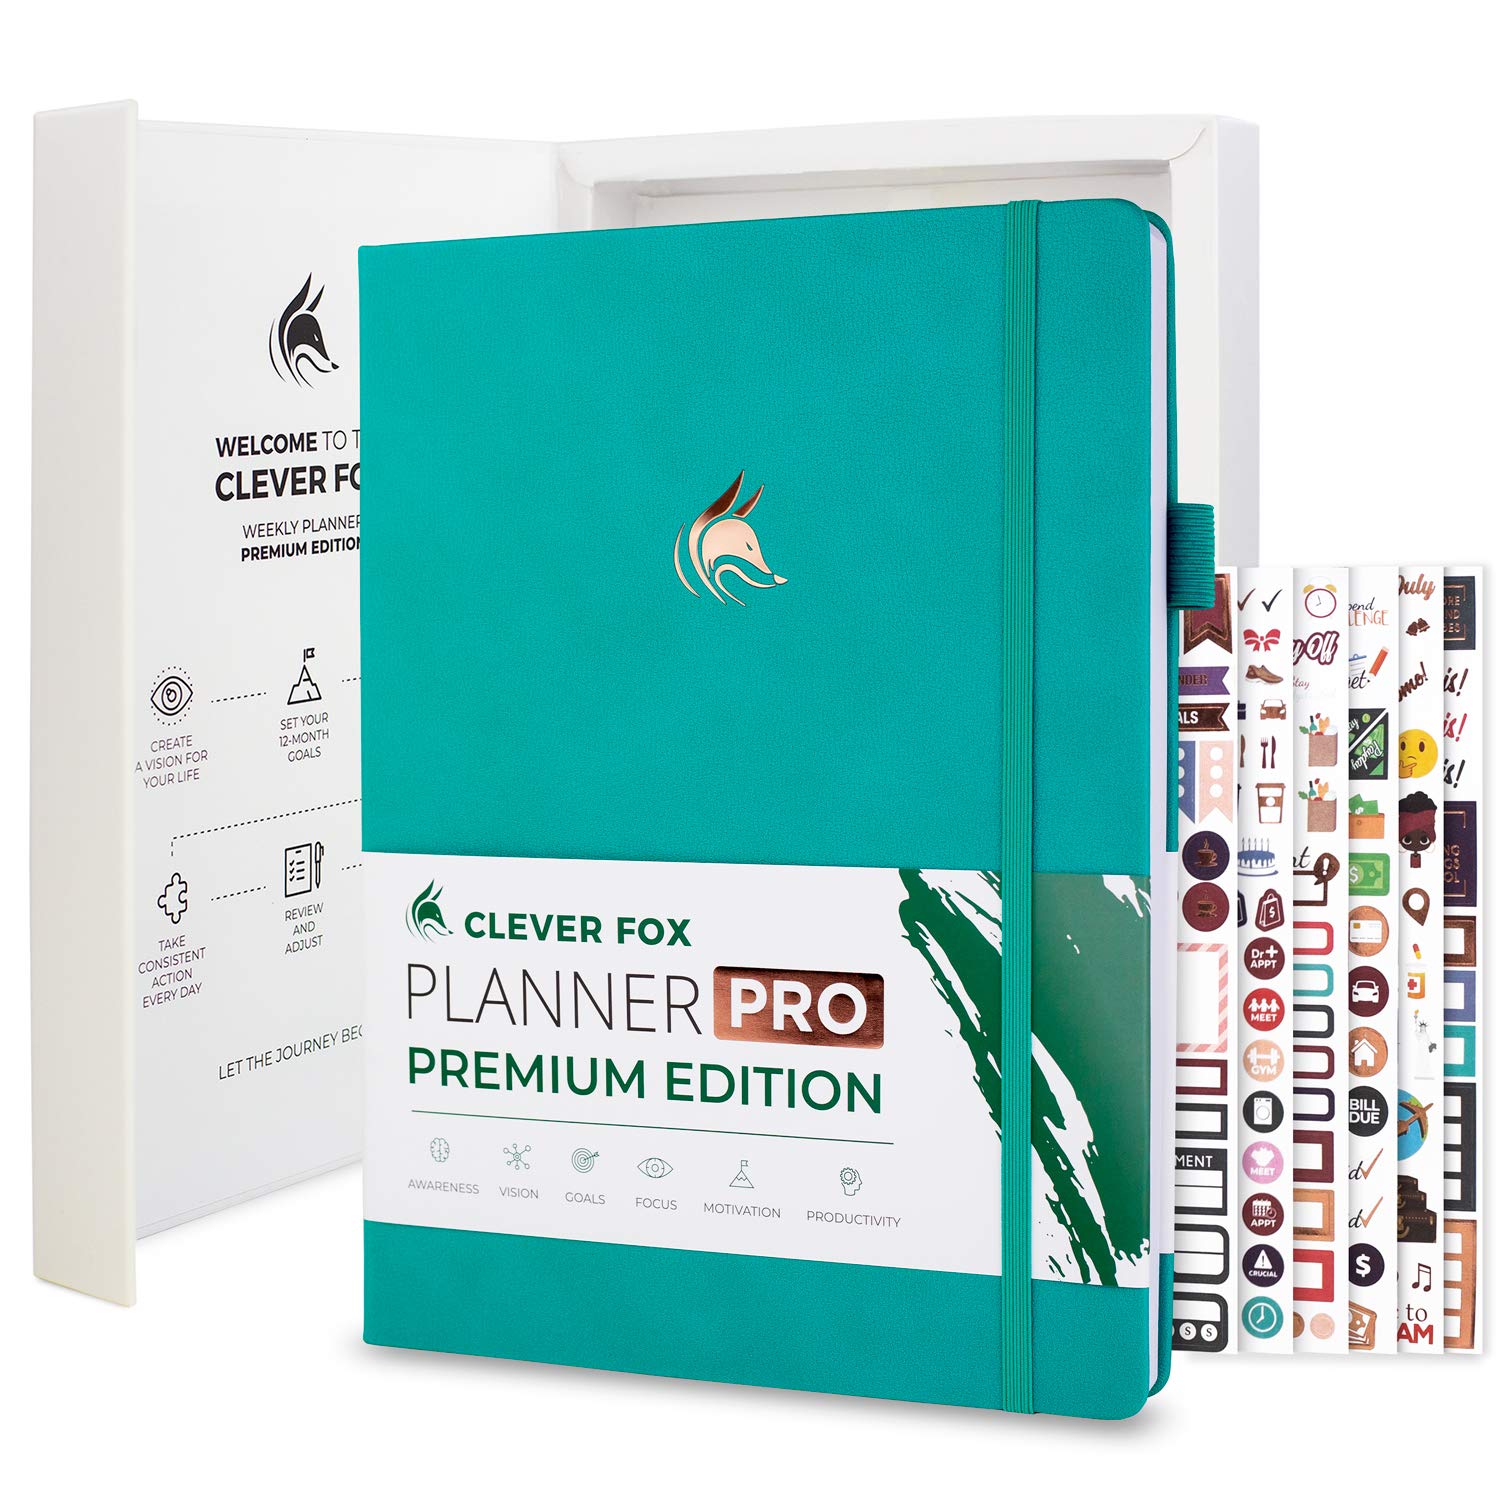
- Undated A4 planner with weekly, monthly, and budgeting sections.
- Combines calendars, goals, and monthly financial planning.
- Includes lay-flat binding, three bookmarks, and a pen loop.
Best For: People who want weekly and monthly life planning alongside financial budgeting pages.
Compact Monthly Budget Book
Clever Fox Budget Book 2.0 – Simple Budgeting Planner for Beginners – Financial Notebook with Money Spending, Debt & Bill Tracker (Hot Pink)
The Clever Fox Budget Book 2.0 keeps monthly money planning in a compact format. Each month has space for a budget, goals, bills, purchases, and day-to-day expenses, with two dotted note pages for extra calculations.
Its eight savings trackers, eight debt trackers, and regular bill tracker suit someone who wants more than a basic expense log without carrying a large book. The 5.3 by 7.7 inch size is paired with a receipt pocket, pen loop, and ribbon bookmark.
Choose it if portability matters; its monthly structure is less specialized than a planner organized around biweekly pay periods.
Best For: Beginners who want a portable monthly planner with dedicated savings, debt, and bill trackers.
| Pros | Cons |
|---|---|
|
|
Choose this book if you want a smaller monthly system with separate savings and debt trackers. Its colorful pages and receipt pocket can keep routine money notes together, while the compact size may mean less writing room than the large-format options.
Check that the monthly layout suits your pay schedule, and confirm the included planning duration if you need a specific coverage period.
Biweekly Paycheck Planning
Clever Fox Bi Weekly Budget Planner – Undated Financial Organizer Book – Expense Tracker, Budgeting & Bill Notebook, A5 (Cypress)
This undated planner structures budgeting around biweekly spreads, making it a natural fit for people who divide money management into two-week periods. The pages support budget planning, important dates, payment deadlines, and daily expense tracking.
It also includes annual financial goal setting, a strategy and tactics framework, and a net worth estimate page, so it extends beyond tracking transactions. At 5.8 by 8.3 inches, it is an A5 format with a lay-flat binding, pen loop, elastic band, bookmarks, and a receipt pocket.
Its more detailed structure is useful if you will use those planning prompts; a simpler monthly book may suit lighter tracking better.
Best For: People who prefer to organize budgets and payment deadlines in biweekly sections.
| Pros | Cons |
|---|---|
|
|
This is the clearest fit for shoppers who want budget planning divided into biweekly periods and need to mark payment dates. The annual goals and net worth pages add a broader financial planning layer, while the A5 format remains smaller than the large books in this group.
Before choosing it, consider whether you prefer two-week spreads and whether the available savings or debt tracking matches your routine.
Bills and Paperwork Organizer
Clever Fox Budget Planner & Monthly Bill Organizer With Pockets. Expense Tracker, Budgeting Journal & Financial Book. Large, 8x9.5" (Dark Green)
This large budget planner brings household spending and bill organization together. Its monthly pages support spending plans and daily expense tracking, while twelve laminated bill pockets provide space to keep financial papers with the planner.
It also includes prompts for savings, debt, payments due, and financial goals, giving it a broader role than a standalone expense notebook. The 8 by 9.5 inch format offers room for planning, but takes more space than the compact options.
Choose this model if keeping paperwork close to budget notes matters; check whether the large footprint works for your desk or bag.
Best For: Households that want monthly expense tracking alongside labeled storage for bill paperwork.
| Pros | Cons |
|---|---|
|
|
Pick this option when bills and paperwork need to stay near monthly budget notes. The laminated pockets distinguish it from planners that focus mainly on tracking and goal prompts.
Its large 8x9.5-inch format provides a more substantial workspace but is less portable than a compact book. Check the physical size against where you plan to use it, and verify the planning duration if you need a full-year layout.
Cash Envelope and Debt Tracking
Clever Fox Budget Planner – Coiled Finance Book, Monthly Financial Journal, Budgeting Organizer & Expense Tracker Notebook, 8.5x9.5″ (Rose Gold)
This spiral budget planner combines monthly budget plans and reviews with an expense tracker, bill tracker, check register, and dedicated savings and debt tracking. It is undated and lasts twelve months, so the calendar can begin when you are ready to use it.
The large 8.5 by 9.5 inch format leaves room for detailed entries, and the package includes three durable cash envelopes and a receipt pocket. That makes it particularly suited to a cash-based budgeting routine.
The tradeoff is size: it is one of the larger options here, so consider where you will keep and write in it before buying.
Best For: Budgeters who want a large monthly planner with cash envelopes, savings, and debt trackers.
| Pros | Cons |
|---|---|
|
|
Choose this planner if cash envelopes are part of your budgeting routine and you want several tracking tools in one large book. The combination of monthly reviews, a check register, and savings and debt pages supports detailed management.
Its twelve-month undated format offers a defined coverage period, while the large footprint is the main practical tradeoff. Check the page organization for your preferred paycheck rhythm before committing.
Budgeting Within a Weekly Life Planner
Clever Fox Planner Pro Premium – Luxurious Weekly & Monthly Planner with Budget Organizer for Productivity & Goals, Undated, A4 (Viridian)
The Planner PRO Premium combines broader life organization with monthly budgeting sections. It has undated weekly planning pages, monthly calendars, goal-setting tools, and financial planning pages, allowing appointments and money plans to share one book.
Its A4 format provides a spacious layout, while lay-flat binding, three bookmarks, an elastic band, pen loop, and pocket support regular use. This is a budget planner for someone who also wants productivity and goal planning, rather than a finance-only notebook.
The larger format and broader page mix may be unnecessary if your priority is simply recording bills and expenses.
Best For: People who want weekly and monthly life planning alongside financial budgeting pages.
| Pros | Cons |
|---|---|
|
|
Select this if you want one planner for your schedule, goals, and budget. Its weekly and monthly life-planning pages set it apart from the dedicated budget books, though the financial sections are part of a wider system rather than the sole focus.
The spacious A4 layout may work well on a desk and be less convenient on the go. Check how much of the book is devoted to budgeting for your preferred level of financial detail.
How to Choose Budget Planners
How We Picked Budget Planners
These five planners all include concrete tools for organizing budgets or tracking expenses, but they serve different routines. The selection covers monthly budget books, a planner with biweekly spreads, an option with bill pockets, a cash-envelope format, and a life planner that includes financial pages.
That keeps the comparison focused on useful differences in schedule, storage, and the amount of planning structure.
A budget planner should match how you already handle money. Consider whether you think in monthly or biweekly periods, whether you need room for goals and reviews, and whether bills or receipts need to stay with your notes.
Format also matters: a large book can offer more writing room, while a smaller one is easier to carry.
Comparing Budget Planners
The strongest distinction is how each book organizes the work. The Budget Book 2.0 is compact and centers on monthly plans with savings and debt trackers.
The biweekly planner gives each two-week period more explicit attention, while the large monthly bill organizer adds twelve pockets for paperwork. The spiral planner adds cash envelopes and a check register.
The Planner PRO Premium folds budgeting into weekly and monthly life planning.
Check the page rhythm before choosing. If you budget after each paycheck, biweekly spreads may feel more natural than a monthly overview.
If you mainly review expenses once a month, a monthly budget and expense tracker may be enough. People who want to keep cash categories or bill papers close to their records should compare the included envelopes and pockets rather than focusing on the planner label alone.
| Product | Standout features | Best for |
|---|---|---|
| Clever Fox Budget Book 2.0Check Price |
| Beginners who want a portable monthly planner with dedicated savings, debt, and bill trackers. |
| Clever Fox Bi Weekly Budget PlannerCheck Price |
| People who prefer to organize budgets and payment deadlines in biweekly sections. |
| Clever Fox Budget Planner & Monthly Bill OrganizerCheck Price |
| Households that want monthly expense tracking alongside labeled storage for bill paperwork. |
| Clever Fox Budget Planner SpiralCheck Price |
| Budgeters who want a large monthly planner with cash envelopes, savings, and debt trackers. |
| Clever Fox Planner PRO PremiumCheck Price |
| People who want weekly and monthly life planning alongside financial budgeting pages. |
Choosing a Planner for Monthly Bills and Expenses
Look for a clear place to plan bills and purchases, then a separate way to record what you spend. The Budget Book 2.0 pairs monthly budgets with a dedicated expense tracker and bill tracker.
The large organizer also includes daily expense tracking and pockets for financial papers. These layouts suit different needs: one prioritizes portability, the other keeps paperwork alongside the planning pages.
If debt payoff or savings are active goals, count the dedicated tracker pages among your decision factors. The compact book includes eight savings and eight debt trackers; the spiral planner includes eight savings and twelve debt trackers.
Those page counts may matter more than extra notes space if you are tracking multiple goals at once.
Finding the Right Size and Budgeting Format
The selected books range from compact formats to large desk-oriented pages, and one A4 life planner. Think about where you will write: a planner used at home can be larger, while one carried regularly may need to fit your everyday bag.
Binding and included accessories also affect routine. The biweekly planner has lay-flat binding and a receipt pocket; the spiral options have pockets, and one includes cash envelopes.
Undated pages help avoid tying a purchase to a particular calendar start, but coverage differs by planner. The spiral planner specifies twelve months, and the biweekly planner also lasts twelve months.
Check the expected planning period for the other formats if you want a fixed annual budget cycle.
Who Should Buy Which Budget Planner?
Choose the Budget Book 2.0 for a compact monthly routine with savings and debt tracking. Pick the biweekly planner if payment dates and two-week budgeting periods shape your process.
The large bill organizer suits people who want papers stored alongside budget pages, while the spiral planner is the fit for cash envelopes and detailed monthly tracking.
Choose the Planner PRO Premium if scheduling, goals, and monthly budgets belong in the same book. Before buying, compare the physical format with where you will use it and make sure its budgeting cadence and tracker pages fit your actual routine.